BOQ cost is the planned cost of a project: BOQ quantity multiplied by BOQ rate. Actual cost is what the project really consumed. The gap between them is construction cost variance.
That gap shows whether project costs are staying within the planned cost envelope and where margin pressure may be developing. This article shows how to split variance by material, labour and subcontractor cost, and correct it while the project runs.
What Is BOQ vs Actual Cost in Construction?
A priced BOQ is a commitment: a quantity of work at a set rate; actual cost is what it took to deliver.
| Term | What it means | Where it comes from |
|---|---|---|
| BOQ / planned cost | BOQ quantity × BOQ rate | Priced BOQ |
| Project budget | BOQ plus approved changes | Commercial team |
| Committed cost | Value locked in POs | Procurement |
| Actual cost | Consumption, certified bills | Site, stores, accounts |
| Cost variance | Actual − planned | Cost report |
Why BOQ vs Actual Cost Matters
Construction businesses lose money in small leaks — a rate revision, extra consumption, an unbilled claim — and variance tracking gives early exposure.
How to Calculate BOQ vs Actual Cost
A positive result is an overrun; a negative result is a saving only if the full scope was executed.
The comparison only works if both sides represent the same executed scope: at 40% completion, compare actual cost with the BOQ cost for that 40% of work, not the full-project BOQ, or the variance will look favourable and hide a problem that surfaces later.
How to Identify the Reason Behind Cost Variance
Every variance comes from quantity or rate.
| Driver | Problem sits with | Check |
|---|---|---|
| Quantity | Site execution, design | Consumption vs allowance |
| Rate | Procurement | PO vs BOQ rates |
| Both | Scope change | Variation orders |
BOQ vs Actual Cost: Worked Construction Example
A residential tower at 65% completion, planned cost prorated to executed work.
| Cost Component | BOQ / Planned Cost | Actual Cost | Variance | Variance % |
|---|---|---|---|---|
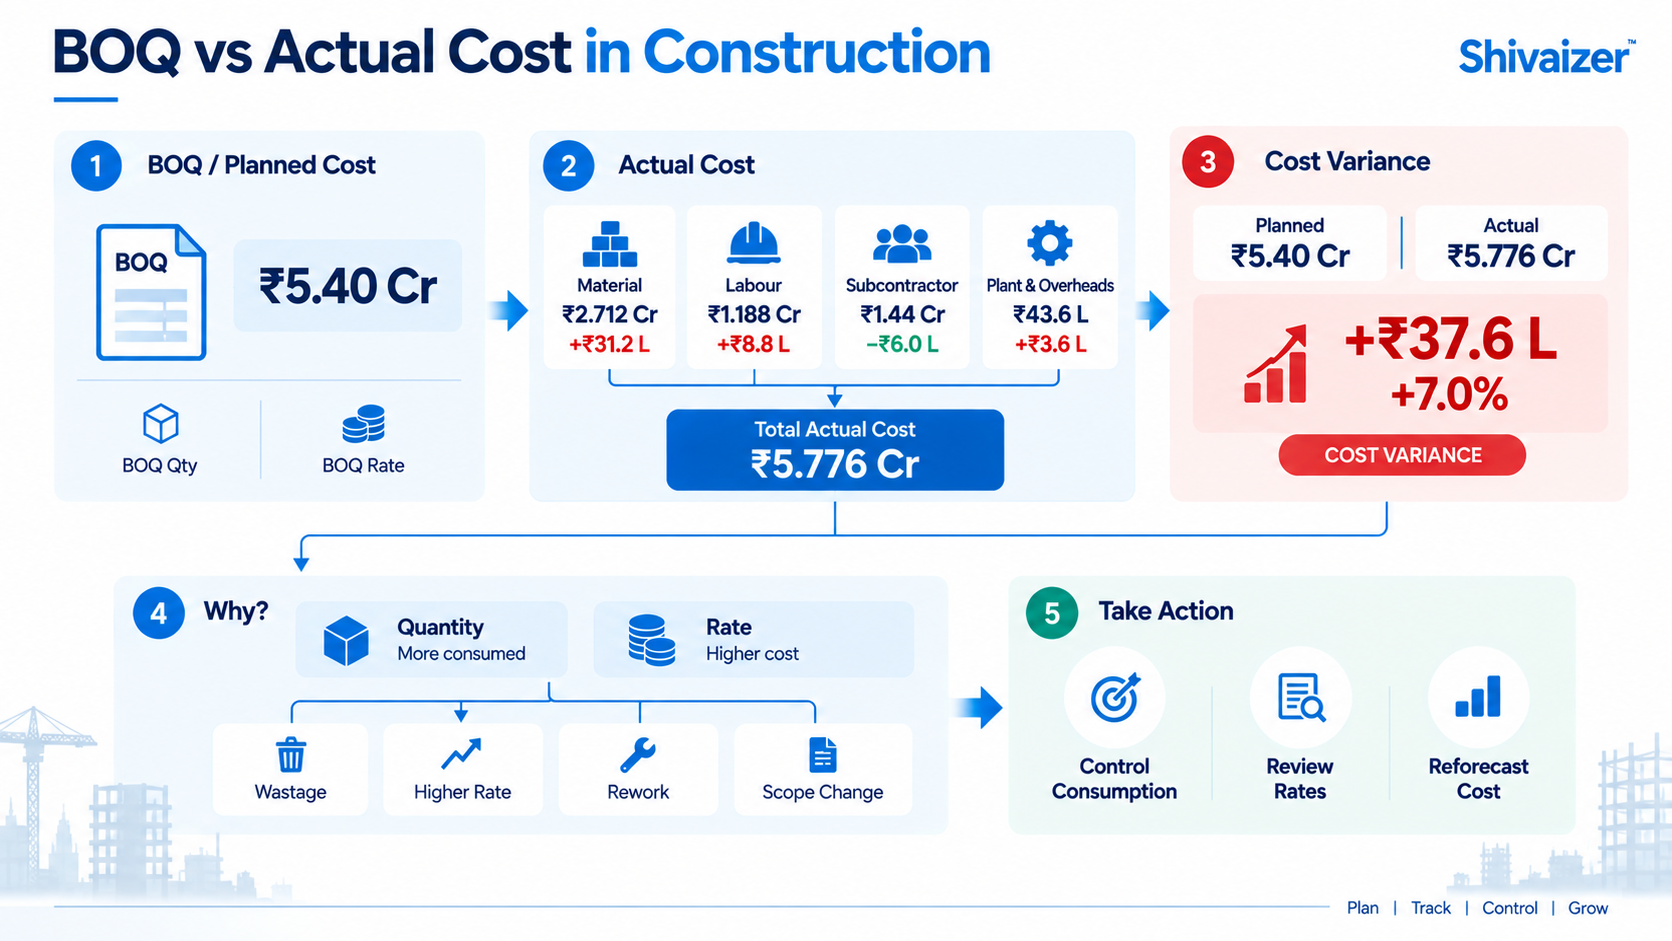
| Material | ₹2,40,00,000 | ₹2,71,20,000 | ₹31,20,000 | +13.0% |
| Labour | ₹1,10,00,000 | ₹1,18,80,000 | ₹8,80,000 | +8.0% |
| Subcontractor | ₹1,50,00,000 | ₹1,44,00,000 | −₹6,00,000 | −4.0% |
| Plant, hire, overheads | ₹40,00,000 | ₹43,60,000 | ₹3,60,000 | +9.0% |
| Total | ₹5,40,00,000 | ₹5,77,60,000 | ₹37,60,000 | +7.0% |
The headline is 7%, but material contributes ₹31.2 lakh of the ₹37.6 lakh gap, so the investigation starts there. Quantity or rate? Steel consumed 9% above BOQ allowance at contracted rates points to wastage; the same quantity at a higher rate points to procurement. The subcontractor under-run needs equal scrutiny before it is called a saving.
How to Track Material Cost Variance Against BOQ
Material is a major source of construction cost variance because its cost trail runs through procurement, storage, issue and consumption, where quantity or value can drift from the BOQ.
Tracking purchases alone is the classic mistake: material in the store is inventory, not cost. Common causes:
- Consumption beyond the BOQ allowance
- Purchase rate above the BOQ rate
- Wastage, breakage, theft, double handling
- Unplanned purchases outside the requisition process
How to Track Labour Cost Variance
Labour cost variance is a project-cost question, not an HR one: compare planned labour cost for executed work against actual cost booked to it.
Typical causes:
- Extra labour-days for the same output — a productivity gap
- Overtime and night-shift premiums to recover slippage
- Duration extended by material or drawing delays
Track gangs by activity.
How to Track Subcontractor Cost Variance
Subcontractor variance surfaces late; it depends on site measurement.
What drives it:
- Work order rates agreed above the BOQ rate
- Extra items executed without a revised order
- Site measurement differing from billed measurement
- Escalation clauses, idling charges, claims
Investigate a favourable subcontractor variance before calling it a saving; uncertified bills can inflate it.
Why Committed Cost Should Be Tracked Before Actual Cost
Actual cost is history; committed cost is the future you have already signed for.
Example: a cost head budgeted at ₹80 lakh shows ₹52 lakh booked, so the report looks comfortable. But POs of ₹61 lakh and work orders of ₹27 lakh are already released — ₹88 lakh committed against ₹80 lakh. The overrun exists today; the invoices have not arrived.
How to Separate Approved Scope Changes From Cost Overruns
Not every variance is leakage; mixing approved changes with overruns destroys report credibility.
| Baseline | Value |
|---|---|
| Original BOQ | ₹1.00 Cr |
| Approved change order | ₹10 Lakh |
| Revised approved budget | ₹1.10 Cr |
| Actual cost | ₹1.08 Cr |
Against the original BOQ the project looks 8% over; against the revised budget it is 1.8% under. For cost-control reporting, keep the original BOQ as baseline and measure performance against the revised approved budget.
How to Monitor BOQ vs Actual Cost During Project Execution
Run this monthly cycle:
Variance found early can be recovered; at handover it is only an explanation.
Common Causes of Construction Cost Variance
| Cause | What changes | What to check |
|---|---|---|
| Material rate variance | Rate above BOQ | PO vs BOQ rate |
| Excess consumption | Quantity above BOQ | Issue slips vs allowance |
| Wastage | Higher consumption | Storage, handling |
| Labour productivity | More labour-days | Planned vs actual output |
| Subcontractor variation | Higher certified value | Measurement vs order |
| Procurement variance | Unplanned buying | Approval trail |
| Design or scope change | Revised quantities | Approved change orders |
| Rework | Extra material, labour | Rework, NCR records |
How to Choose Construction Cost-Control Software
The problem is not arithmetic — the data lives in different places.
Without a connected system: BOQ → Excel → purchase records → site records → labour records → subcontractor records → finance → manual consolidation, weeks late.
With a connected construction ERP: BOQ → Budget → Procurement → Committed Cost → Material Receipt → Site Consumption → Labour → Subcontractor → Actual Cost → Variance → Reporting.
Each stage feeds the next: a purchase order becomes committed cost on release, before material arrives; a receipt updates site inventory; an issue slip converts inventory into consumption against that item; and a labour or subcontractor entry books to the same cost head. Because every transaction carries the project and cost head from entry, variance reporting becomes a query, not a monthly reconciliation. With Shivaizer, teams connect BOQ, procurement, inventory and project costing in one workflow — which is why variance analysis belongs inside construction management software, not a spreadsheet.
How Can Construction Companies Automate BOQ vs Actual Cost Tracking?
Questions that separate real automation from cosmetic reporting:
Can BOQ and actual cost sit in one system? Otherwise reconciliation returns.
Can consumption map to BOQ items? Otherwise only purchases are visible.
Can commitments be monitored? An early warning.
Can labour be tagged to the project and BOQ activity worked on? Otherwise labour cost sits in a payroll total, not against the work produced.
Can subcontractor cost be tagged to the project and work order? Untagged bills hide which scope drives variance.
Can variance be seen during execution, not just at completion? A monthly view allows correction; a final report only explains.
What Should Construction Cost-Control Software Track?
- BOQ management and budgeting by cost head
- Project-linked procurement, committed cost visibility
- Material receipt and consumption against BOQ
- Variance analysis and reporting
Shivaizer ERP brings these workflows together so costs are reviewed from one system, not reassembled monthly.
BOQ vs Actual Cost Tracker Template
| BOQ Item | BOQ Qty | Actual Qty | BOQ Rate | Actual Rate | BOQ Cost | Actual Cost | Variance % | Reason | Corrective Action |
|---|---|---|---|---|---|---|---|---|---|
| M25 concrete (cum) | 1,200 | 1,265 | 6,400 | 6,550 | 76,80,000 | 82,85,750 | +7.9% | Wastage, rate rise | Revise pour planning |
| Reinforcement (MT) | 180 | 191 | 72,000 | 74,500 | 1,29,60,000 | 1,42,29,500 | +9.8% | Excess consumption | Bar-bending check |
Copy this into Excel or Google Sheets and add cost head, quantity variance, rate variance, owner and status columns; once populated project-wide, the sheet doubles as the variance report and a monthly cost-control register.
Common BOQ vs Actual Cost Tracking Mistakes
- Comparing total project cost without cost-head detail
- Using an outdated BOQ
- Ignoring committed cost until invoices arrive
- Mixing approved changes with overruns
Troubleshooting BOQ vs Actual Cost Reporting
| Problem | Possible cause | What to check |
|---|---|---|
| Actual cost too high | Another project’s costs booked | Project tagging on POs |
| Material variance high | Purchases counted as consumption | Store issue records |
| Purchase cost above BOQ | Rate or specification change | PO vs BOQ rate |
| Subcontractor variance high | Extra items without order | Measurement sheets |
| Budget exceeded after revision | Original BOQ as baseline | Approved change orders |
| Actual cost unusually low | Bills not booked | Pending supplier bills |
| Duplicate project cost | Bill entered twice | Invoice reference, GRN |
FAQs
How do you calculate BOQ vs actual cost in construction?
How do I track material cost against BOQ?
How do I track labour and subcontractor variance against BOQ?
Should committed cost be included in construction cost analysis?
How often should construction companies review BOQ vs actual cost?
Can construction ERP automate BOQ vs actual cost reporting?
Conclusion
Comparing BOQ vs actual cost is only the starting point. The value lies in knowing whether the gap came from quantity or rate, and acting in time.
See how Shivaizer connects BOQ, procurement, site consumption, subcontractor cost and actual project cost in one workflow